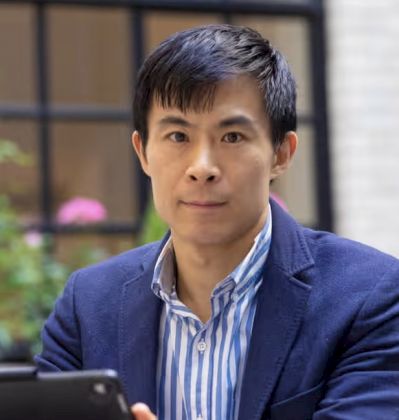
Filippo Gaddo, Managing Director at Alvarez & Marsal, SPE Councillor and host of the Econ Thoughts SPE Podcast, spoke with Alex Edmans, Professor of Finance at London Business School, about behavioural finance, market efficiency and why even sophisticated investors can make seemingly irrational decisions. The discussion centres on Alex’s new book, The Madness of Markets, to be released on the 16th September, and also explores some of the connections with his previous work on evidence, responsible business and investment.
The conversation begins with a fundamental question: are financial markets rational? As a good economist, Alex answers with … ‘it depends’. Markets often react quickly to relevant information, but full market efficiency is an extremely demanding standard. Investors can underreact to information that matters while simultaneously overreacting to news, narratives or fashions that have little connection to fundamentals. Importantly, these mistakes do not appear to be entirely random: many are systematic, creating patterns that investors may potentially exploit. One example is momentum. Stocks that have performed strongly over the previous few months have historically tended to continue outperforming for a period, while recent losers have tended to continue underperforming. One explanation is that investors fail to incorporate new information fully or quickly enough. Alex distinguishes between simply having access to information and understanding its implications. He compares investing to chess rather than poker: the problem may not be that the information is hidden, but that some people are better than others at interpreting the information that everybody can see. Amazon Web Services provides one example – the foundations of what became an enormously important business were visible years before investors fully appreciated their significance.
Over longer periods, however, markets can display the opposite tendency: overreaction and eventual reversal. This leads Filippo and Alex to discuss whether the current enthusiasm surrounding artificial intelligence could constitute a bubble. Alex argues that the evidence is ambiguous. Strong recent performance might point towards over-exuberance, but valuations also need to be assessed against earnings and the underlying economic potential of AI. More broadly, he stresses that apparently irrational investment decisions cannot be judged without understanding an investor’s objectives and constraints. An investor who sells before the peak, or a fund manager who remains invested in an asset they believe to be overvalued, may have entirely rational reasons for doing so. The discussion also explores the power of narratives, social contagion and AI in investment decisions. More information does not necessarily produce better decisions. Investors can use AI and data selectively to reinforce a conclusion they have already reached rather than to challenge it.
Filippo and Alex then consider the implications for public policy and financial education. Alex is cautious about government intervention in individual investment choices, but sees a strong case for better financial literacy and greater transparency. Retail investors may be attracted by supposedly “zero commission” trading without understanding costs such as bid-ask spreads, or may take substantial risks in complex products they do not fully understand. Better education about diversification, risk and investment fundamentals could improve decision-making without requiring policymakers to prohibit particular investments. The same behavioural biases can also affect policymakers themselves. Governments may overreact to a highly visible individual case and introduce regulations without establishing whether the problem is systematic or considering unintended consequences. In that sense, some of the forces behind the “madness of markets” can also operate in politics and regulation.
Finally, the conversation returns to themes from Alex’s earlier book Grow the Pie. Investors do not necessarily seek only financial returns; they may also pursue social or moral objectives. But having non-financial objectives does not remove the need for rigorous analysis. The discussion concludes by considering why market rationality matters beyond investment returns. Financial markets help determine which companies and projects receive capital. If markets systematically undervalue productive opportunities, worthwhile investment may be constrained; if they overvalue fashionable sectors, too much capital may flow into weak projects. The madness of markets therefore matters not only for investors, but for the real economy.
Alex Edmans is Professor of Finance at London Business School and a leading researcher and commentator on corporate finance, responsible business and behavioural finance. He is the author of Grow the Pie and May Contain Lies, as well as his new book The Madness of Markets. His work examines how evidence, incentives and human behaviour shape the decisions of investors, companies and policymakers.
You can find us on Spotify or Apple podcasts.
Interview with Alex Edmans
This video is hosted by Vimeo. It opens only when you choose to watch it.
WatchMore Podcasts
Interview with Mike Munger
Filippo Gaddo, Managing Director at Alvarez & Marsal, SPE Councillor and host of the Econ Thoughts SPE Podcast, spoke with Michael Munger, Professor of...
Interview with Branko Milanovic
Filippo Gaddo, Managing Director at Alvarez & Marsal, SPE Councillor and host of the Econ Thoughts SPE Podcast, spoke with Branko Milanovic, Research...
Interview with Jesús Fernández-Villaverde
Filippo Gaddo, Managing Director at Alvarez & Marsal, SPE Councillor and host of the Econ Thoughts SPE Podcast, speaks with Jesús...